The 50-30-20 Rule Explained for Salaried Professionals
by financeretire · Published · Updated
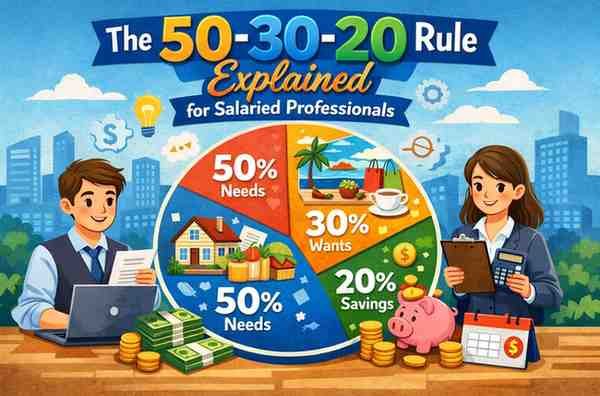
Managing money effectively is a skill every salaried professional must master. No matter how much you earn, if your spending habits aren’t balanced, you may find yourself struggling by month-end. That’s where the 50-30-20 rule comes in — a simple yet powerful budgeting method that helps you spend, save, and invest smartly.
In this article, we’ll break down what the 50-30-20 rule is, how to apply it in real life, and why it’s perfect for salaried individuals in India.
1. What Is the 50-30-20 Rule?
The 50-30-20 rule is a personal finance formula designed to help you allocate your monthly income efficiently.
It divides your take-home salary into three clear categories:
-
50% for Needs
-
30% for Wants
-
20% for Savings and Investments
This method ensures you cover essentials, enjoy life, and still save for the future — without feeling restricted.
Formula:
👉 (Take-home Salary) = 50% Needs + 30% Wants + 20% Savings
2. Breakdown of the 50-30-20 Rule
Let’s understand each component with examples relevant to salaried professionals.
A. 50% — Needs (Essentials)
These are expenses you must pay every month to live comfortably. They are non-negotiable and form the foundation of your budget.
Examples of Needs:
-
House rent or home loan EMI
-
Groceries and household supplies
-
Electricity, water, and internet bills
-
Transportation or fuel
-
Health insurance premium
-
School fees or essential EMIs
💡 Tip: Try to keep your rent or home EMI under 25–30% of your income to maintain balance.
B. 30% — Wants (Lifestyle Expenses)
These are the things you enjoy but can live without. Wants make life enjoyable, but they should never exceed the limit — otherwise, they eat into your savings.
Examples of Wants:
-
Eating out and food delivery
-
Shopping, clothing, and gadgets
-
Vacations or weekend trips
-
OTT subscriptions (Netflix, Prime Video)
-
Gym memberships or entertainment activities
💡 Tip: You don’t have to cut out all fun — just plan it within the 30% budget.
C. 20% — Savings and Investments
This portion is for building your financial future. Saving and investing consistently will help you achieve long-term goals like buying a home, retiring early, or starting a business.
Examples of Savings and Investments:
-
Emergency fund contributions
-
SIPs in mutual funds
-
Equity or index fund investments
-
Recurring deposits or PPF
-
Retirement corpus (NPS or EPF)
-
Insurance premiums (life and health)
💡 Pro Tip: Automate your savings — set up a SIP or recurring transfer right after salary credit.
3. How to Apply the 50-30-20 Rule in Real Life
Let’s take an example.
Example:
If your monthly take-home salary is ₹80,000, your budget should look like this:
| Category | Percentage | Amount (₹) | Purpose |
|---|---|---|---|
| Needs | 50% | 40,000 | Rent, groceries, bills, fuel |
| Wants | 30% | 24,000 | Dining, shopping, entertainment |
| Savings & Investments | 20% | 16,000 | SIPs, insurance, emergency fund |
This gives you a balanced structure — you can enjoy your salary, cover essentials, and still grow your wealth.
4. Benefits of the 50-30-20 Rule
✅ Simple and Easy to Follow
You don’t need advanced financial knowledge — just basic awareness of your expenses.
✅ Builds Financial Discipline
It helps prevent overspending and ensures consistent savings every month.
✅ Balances Lifestyle and Savings
You enjoy life without guilt while planning for future goals.
✅ Adaptable for All Income Levels
Whether you earn ₹25,000 or ₹2 lakh, the percentage-based system works equally well.
✅ Encourages Early Investing
By allocating 20% toward savings, you automatically create long-term wealth.
5. Adapting the Rule to Your Salary
Everyone’s financial situation is different. You can tweak the ratio slightly depending on your goals.
Examples:
-
If you’re paying high rent (like metro cities): Use 60-20-20.
-
If you’re saving for early retirement: Try 40-30-30.
-
If you have dependents or loans: Adjust savings to 15% temporarily, then increase later.
The goal is not strict compliance — it’s to maintain financial awareness and consistency.
6. Common Mistakes to Avoid
🚫 Counting Wants as Needs:
A Netflix subscription or a new phone isn’t a “need.” Be honest with yourself.
🚫 Not Reviewing Expenses Monthly:
Track your spending regularly to make sure your budget stays balanced.
🚫 Delaying Savings:
Don’t wait for “extra money” to start saving — begin with what you can today.
🚫 Ignoring Inflation:
Revisit your budget every 6–12 months to adjust for rising costs.
7. Tools to Help You Implement the 50-30-20 Rule
Here are some digital tools to automate tracking and budgeting:
-
Walnut / Money Manager: Auto-track income and expenses.
-
ET Money / INDmoney: Manage SIPs, insurance, and investments.
-
Google Sheets: Simple manual budgeting option.
These tools make it easy to stay on top of your financial goals without manual effort.
The 50-30-20 rule is more than just a budgeting formula — it’s a mindset for achieving financial control and freedom.
For salaried professionals, it offers a clear, practical system to manage everyday expenses, enjoy life, and secure the future.
Start today — track your spending, categorize it, and automate your savings. Within a few months, you’ll notice less stress, more savings, and stronger financial confidence.
Remember:
“It’s not about how much you earn, but how wisely you use what you earn.” 💰